Financial Habits That Separate Wealth Builders From Spenders
Discover the key financial habits that set wealth builders apart from spenders. Learn practical strategies to budget, invest, and grow lasting wealth.
Financial Habits That Separate Wealth Builders From Spenders
Building lasting wealth is less about luck and more about consistent habits. While many people dream of financial freedom, only a few turn those dreams into reality. The difference often lies in daily choices: how you earn, spend, and grow your money. Below we outline the core habits that set wealth builders apart from those who simply spend.
1. Mindful Income Management
Wealth builders treat every paycheck as a strategic asset. They prioritize paying themselves first by allocating a fixed percentage to savings or investments before addressing discretionary expenses. This “pay yourself first” rule ensures that growth is built into the income cycle, not an afterthought.
Practical Tip
Set up automatic transfers to a high‑yield savings account or brokerage account the moment you receive your paycheck. Automating the process removes the temptation to spend what you might otherwise save.
2. Strict Budget Discipline
Spenders often lack a clear budget, leading to impulse purchases and hidden debt. Wealth builders create a detailed budget that tracks income, fixed expenses, variable costs, and savings goals. They review it monthly, adjusting for life changes while staying on target.
Practical Tip
Use a zero‑based budgeting app to assign every dollar a purpose. When the month ends, your balance should be zero, indicating that each dollar has a planned use.
3. Strategic Debt Management
Not all debt is bad, but the type and timing matter. Wealth builders focus on eliminating high‑interest debt first—credit cards, payday loans, or personal lines. Once high‑cost debt is cleared, they may consider low‑interest loans for investments such as real estate or business ventures.
Practical Tip
Apply the avalanche method: list debts by interest rate, pay minimums on all, then put extra funds toward the highest rate debt.
4. Continuous Learning and Adaptation
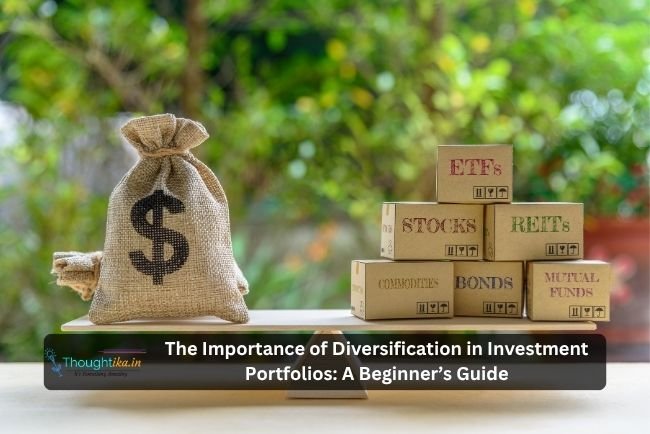
Financial markets evolve, and so should your strategies. Wealth builders stay informed through books, podcasts, and financial news. They adapt their portfolios to changing economic conditions, diversifying across assets to mitigate risk.
Practical Tip
Allocate 10% of your annual income to financial education—books, courses, or seminars.
5. Long‑Term Investment Focus
Spenders chase short‑term gratification, while wealth builders invest with a horizon of years or decades. They prioritize low‑cost index funds, dividend growth stocks, or real estate that appreciates over time. Consistent, dollar‑cost averaging smooths market volatility.
Practical Tip
Set up a recurring investment plan—e.g., $200/month into a diversified ETF—to build wealth steadily.
6. Lifestyle Inflation Control
Income increases can tempt lifestyle upgrades that erase savings growth. Wealth builders resist this by maintaining a modest standard of living and redirecting any salary bump toward savings or investment.
Practical Tip
When a raise arrives, split it: 50% into savings, 30% into investments, 20% for personal enjoyment.
7. Emergency Fund Creation
A robust emergency fund—typically 3–6 months of living expenses—acts as a financial safety net. Wealth builders build this before aggressively investing, ensuring they can weather job loss, medical bills, or market downturns without liquidating investments.
Practical Tip
Open a separate high‑interest savings account and aim to add $1,000 monthly until you hit your target.
8. Regular Financial Health Checkups
Wealth builders schedule quarterly reviews of their financial statements, investment performance, and goal progress. They adjust contributions, rebalance portfolios, and set new milestones based on life events.
Practical Tip
Use a financial dashboard app to visualize income, expenses, net worth, and goal timelines in one place.
9. Mindful Spending Habits
Even when budgeting, the quality of purchases matters. Wealth builders evaluate whether an expense aligns with long‑term goals, values, or offers genuine utility. They often adopt the “30‑day rule” for non‑essential purchases to curb impulse buying.
Practical Tip
Before buying a non‑essential item, wait 30 days. If you still want it, consider whether it truly adds value to your life.
10. Giving Back and Legacy Planning
True wealth includes the ability to give. Wealth builders incorporate charitable giving and estate planning into their long‑term strategy, ensuring their legacy benefits future generations and causes they care about.
Practical Tip
Set up a donor-advised fund or allocate a small percentage of your portfolio to charitable contributions annually.
Adopting these habits transforms financial behavior from reactive spending to proactive wealth building. It takes discipline, but the payoff—a secure, prosperous future—is worth every effort.
What's Your Reaction?